Table of Contents
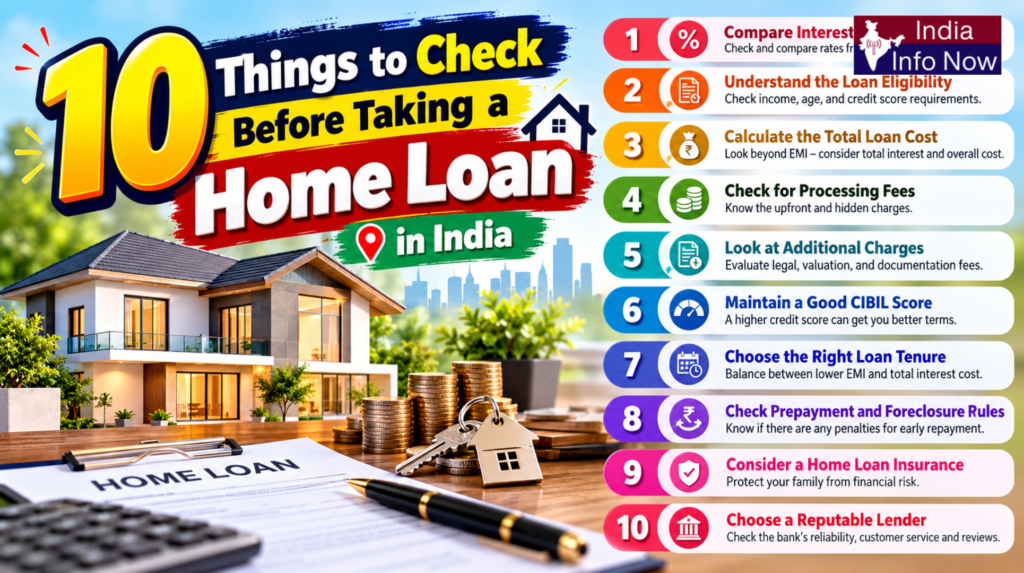
Toggle10 Things to Check Before Taking a Home Loan in India
1. Check Your Home Loan Eligibility
Before applying for a home loan, determine how much you can reasonably borrow. Banks and housing finance companies generally assess your income, age, employment stability, existing financial obligations, credit history, and repayment capacity.
Salaried applicants may need to provide salary slips, bank statements, and income tax returns. Self-employed applicants may be asked for income tax returns, business financial statements, and bank records.
Your eligibility also depends on the lender’s policies and the property’s value. If you apply jointly with an eligible co-applicant, their income may improve your combined repayment capacity.
Tip: Use a home loan eligibility calculator to estimate a suitable loan amount before beginning your property search. Remember that the lender’s maximum eligible amount may be higher than what comfortably fits your budget.
2. Compare Home Loan Interest Rates
The interest rate significantly affects your monthly EMI and the total amount you repay over the loan tenure. Even a small difference in the rate can make a considerable difference over several years.
Home loans generally offer floating interest rates, while fixed-rate or combination options may be available depending on the lender and product.
Floating-rate loans: The interest rate can change according to the applicable benchmark and loan terms. Your EMI, repayment tenure, or both may change.
Fixed-rate loans: The interest rate remains fixed for the period specified in the agreement. Check whether the rate is fixed for the entire tenure or only an initial period.
Combination loans: These may combine fixed-rate and floating-rate periods or components, depending on the product.
Compare offers from several lenders rather than selecting a loan solely because it advertises the lowest starting rate. Also review the benchmark, spread, reset frequency, and applicable conditions.
3. Calculate the Required Down Payment
Most lenders do not finance the entire purchase price of a property. You generally need to contribute a portion of the cost from your own funds, known as the down payment.
The loan-to-value ratio, or LTV, determines the maximum proportion of the property’s eligible value that the lender may finance. The permitted ratio depends on the loan amount, applicable regulations, lender policies, and property assessment.
For example, if a property costs ₹50 lakh and a lender finances 80% of its eligible value, the potential loan amount would be ₹40 lakh. You would need to contribute the remaining ₹10 lakh, subject to the lender’s valuation and eligibility assessment.
Remember that stamp duty, registration charges, legal expenses, and certain other purchase costs may need to be paid separately.
Tip: Start saving for your down payment early and avoid using your entire savings balance. Keep an emergency fund for unexpected expenses after purchasing the property.
4. Understand the Total Cost of the Home Loan
The cost of borrowing is not limited to the interest rate. Additional charges can increase the total amount you pay over the life of the loan.
Before accepting an offer, ask the lender for a complete breakdown of charges, including:
Processing fees
Legal and property valuation charges
Administrative or documentation fees, where applicable
Applicable insurance premiums
Charges for certain loan-related services
Prepayment or foreclosure charges, where legally applicable
Review the lender’s Key Facts Statement (KFS), where applicable, and the loan agreement. Check the Annual Percentage Rate (APR) or equivalent disclosed borrowing-cost information, which can help you compare the overall cost of competing offers.
Do not rely only on verbal assurances about fees. Ask for the applicable charges in writing before signing the agreement.
Loan tenure determines how long you will repay the loan. A longer tenure usually reduces your monthly EMI but increases the total interest paid if the rate and other assumptions remain unchanged. A shorter tenure generally increases the EMI but can reduce the overall interest cost.
For example, a ₹10 lakh loan at an assumed annual interest rate of 10.4% would have approximately the following EMIs under a standard monthly reducing-balance calculation:
| Loan tenure | Approximate monthly EMI |
|---|---|
|
20 years |
₹9,917 |
|
30 years |
₹9,073 |
These figures are illustrative. Actual repayments depend on the lender’s rate, fees, repayment structure, and terms.
Choose an EMI that leaves enough room in your monthly budget for household expenses, savings, insurance, education costs, and emergencies. Do not choose the longest possible tenure simply to obtain a lower EMI without considering the total interest cost.
Your credit profile can influence your eligibility, the interest rate offered, and the lender’s decision. A strong credit history may improve your chances of obtaining favourable terms, although approval is never guaranteed.
Before applying:
Check your credit report for errors.
Pay existing EMIs and credit card bills on time.
Reduce unnecessary outstanding debt.
Avoid submitting multiple loan applications within a short period.
Correct inaccurate information through the relevant credit bureau or lender.
Lenders may also consider your income, job stability, existing liabilities, and the property’s legal and technical status.
Tip: Review your credit report well before applying so you have time to address any discrepancies.
7. Verify the Property's Legal and Technical Documents
The key difference is how interest is calculated.
8. Understand Prepayment and Foreclosure Rules
Inflation reduces the purchasing power of money because goods and services generally become more expensive over time.
If your savings earn a return below the inflation rate, your money may grow in nominal terms while losing purchasing power. If the return exceeds inflation, your savings may gain purchasing power before taxes and fees.
For this reason, compare the return on your investments with inflation rather than looking only at the amount displayed in your account.
No investment can guarantee protection against inflation in every situation. Choosing appropriate investments depends on your time horizon, risk tolerance, and financial needs.
9. Understand the Tax Benefits on Home Loans
Home loans may offer tax benefits, subject to the applicable provisions, property usage, ownership conditions, loan purpose, and tax regime.
Potentially relevant provisions include:
Section 24(b): May provide a deduction for eligible home loan interest, subject to applicable conditions and limits.
Section 80C: May provide a deduction for eligible principal repayment under the old tax regime, within the overall limit and subject to the relevant conditions.
Other provisions: Certain additional deductions may apply to eligible borrowers or loans if the statutory conditions are satisfied.
Tax treatment can differ between self-occupied and let-out properties and between the old and new tax regimes. Eligibility and restrictions can also change with amendments to tax law.
Do not choose a home loan solely for its potential tax savings. Calculate whether the property and loan are affordable even without assuming a particular deduction. Consult a qualified tax professional for advice based on your circumstances.
10. Prepare All Required Documents Before Applying
Compound interest is one of the most important concepts to understand when planning your financial future. By allowing earnings to generate additional earnings, it can help small savings grow into a meaningful financial reserve over time.
The most practical approach is to start early, save consistently, reinvest earnings when suitable, choose investments that match your goals, and review your progress periodically.
You do not have to wait until you earn a high salary to begin. Start with an amount you can comfortably afford, protect your emergency savings, and increase your contributions as your financial situation improves.
Final Checklist Before Taking a Home Loan
Before committing to a home loan, make sure you have:
Checked your eligibility and credit report
Compared interest rates from multiple lenders
Saved enough for the down payment and purchase costs
Calculated an affordable EMI
Compared processing fees and other charges
Selected a suitable repayment tenure
Verified the property’s legal documents
Understood prepayment and foreclosure conditions
Reviewed potential tax benefits
Read the loan agreement and applicable disclosures carefully
Conclusion: 10 Things to Check Before Taking a Home Loan in India
Taking a home loan is an important financial decision that requires careful planning. A low interest rate alone does not necessarily make a loan the best choice. You should also consider the total borrowing cost, EMI affordability, repayment flexibility, property documentation, and your long-term financial goals.
Compare lenders, understand the loan terms, and keep sufficient savings for emergencies before making a commitment. If you plan carefully, a home loan can help you purchase a property while keeping your finances manageable.
Frequently Asked Questions
1. What should I check before taking a home loan in India?
A beginner can start by setting financial goals, assessing risk tolerance, opening a Demat and trading account with a suitable registered broker, and learning how shares and mutual funds work. Start with an affordable amount and research investments before purchasing them.
2. How much down payment is required for a home loan?
Interest is added to your balance at the applicable compounding interval. Future interest is then calculated on the increased balance, allowing savings to grow over time.
3. What credit score is needed for a home loan?
The standard formula is \(A=P(1+r/n)^{nt}\), where \(P\) is the principal, \(r\) is the annual interest rate, \(n\) is the number of compounding periods per year, and \(t\) is the number of years. Compound interest equals \(A-P\).
4. Is a fixed or floating interest rate better for a home loan?
Common requirements include a PAN card, bank account details, identity and address verification, a mobile number, and an email address. Additional documents may be requested depending on the broker’s KYC process.
Most Popular
-
 Diwali Health Tips for Senior Citizens: 15 Safety Tips for a Happy Festival
-
 15 Easy Diwali Decoration Ideas to Make Your Home Look Beautiful
-
 How to Celebrate Diwali on a Budget: 12 Smart Money-Saving Tips
-
 Diwali 2026: 15 Interesting Facts You Should Know About the Festival
-
 Is Digital Gold Safe in India? Benefits, Risks and Investment Tips